

Under the patronage of His Highness Sheikh Mohamed bin Zayed Al Nahyan, President of the UAE, in his capacity as Ruler of Abu Dhabi
تحت رعاية صاحب السمو الشيخ محمد بن زايد آل نهيان ، رئيس الدولة "حفظه الله"، بصفته حاكماً لإمارة أبوظبي
Explore cutting-edge solutions, build valuable connections,
and stay ahead of the trends transforming global energy.
Across 13 conference programmes and 380+ sessions, speakers will share
diverse perspectives and discuss actionable outcomes aimed at
accelerating the transition to a cleaner, more secure energy future.
Explore ADIPEC insights, announcements,
content and images of relevance
to members of the media.
For media enquiries email media@adipec.com
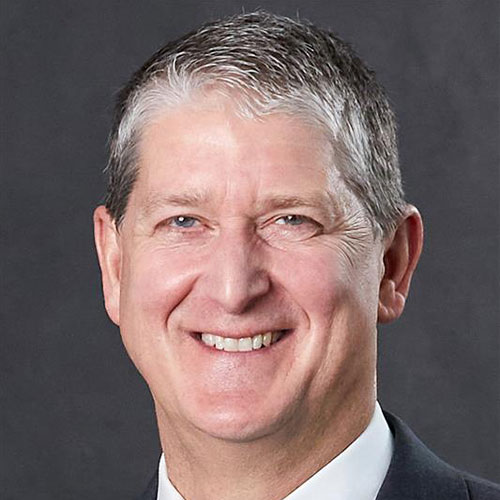
Roger Kearns joined NOVA Chemicals as President and CEO in June 2023. Kearns leads the company’s ambition to reshape plastics to be our customers’ first and best choice. He is a senior executive with extensive international and industry leadership experience in the commodity and specialty chemicals spaces. Prior to joining NOVA Chemicals, Kearns was Chief Operating Officer at Westlake Corporation, the global diversified manufacturer of essential products (NYSE: WLK). He joined Westlake as Executive Vice President of Vinyl Chemicals in 2018 after previously serving for 32 years at Solvay, a global leader in materials, solutions, and chemicals. A member of Solvay’s Executive Committee for 10 years, Kearns held progressively senior roles on both the operational and investment sides of the business across a number of international markets, including the United States, Europe, and Asia. Kearns holds a Bachelor of Chemical Engineering from Georgia Tech and a MBA from Stanford. He currently serves on the Advisory Board for Georgia Institute of Technology’s School of Chemical & Biomolecular Engineering and is a former member of the Georgia Tech President’s Advisory Board. Kearns also is a board member of the Alliance to End Plastic Waste (AEPW) where he formerly served as Chair of the Audit Committee. In addition, he serves as a board member of the American Chemistry Council (ACC), sits on its Board Global Strategy, and serves as chair of the Board Plastics Committee. He is chair of the Society of Chemical Industry (SCI) America. He has been listed as “one to watch” in the 2024 Top 40 Power Players by ICIS, a global ranking of the leading CEOs and senior executives making the greatest positive impact on their companies and the chemicals industry.

dmg events is a global exhibitions and conferences organiser, with a portfolio of over 80 events focusing on diverse industries, from energy, construction and transport to design and hospitality. More than 425,000 visitors attend our events annually, creating opportunities to network, do business, overcome challenges and discover emerging industry opportunities.
Member of


