

Under the patronage of His Highness Sheikh Mohamed bin Zayed Al Nahyan, President of the UAE, in his capacity as Ruler of Abu Dhabi
تحت رعاية صاحب السمو الشيخ محمد بن زايد آل نهيان ، رئيس الدولة "حفظه الله"، بصفته حاكماً لإمارة أبوظبي
Explore cutting-edge solutions, build valuable connections,
and stay ahead of the trends transforming global energy.
Across 13 conference programmes and 380+ sessions, speakers will share
diverse perspectives and discuss actionable outcomes aimed at
accelerating the transition to a cleaner, more secure energy future.
Explore ADIPEC insights, announcements,
content and images of relevance
to members of the media.
For media enquiries email media@adipec.com

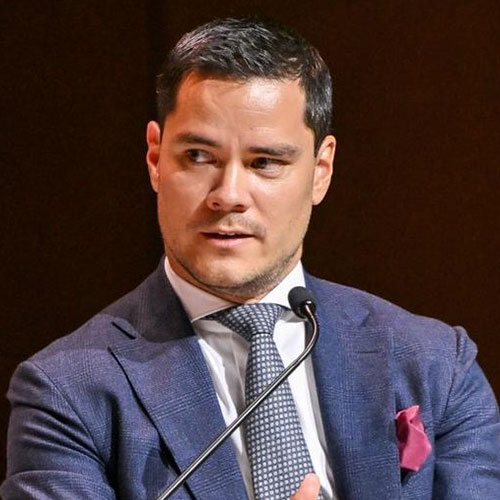
Charlie is Chief Executive Officer at the Global Impact Coalition (GIC), a CEO-led cross-industry accelerator platform founded by some of the world’s leading chemical companies. GIC is focused on enabling new business models and investment in proof of concepts that drive net zero and circularity objectives. Charlie works closely with the CEO Advisory Board and Executive Committee, composed of c-suite leaders from GIC member companies, and he guides a team of partners and collaborators to drive projects from ideation to spin-off. Previously, Charlie was at the World Economic Forum, where he led the incubation and development of the Global Impact Coalition as a spin-off from the Low Carbon-Emitting Technologies (LCET) platform. Prior to the Forum, Charlie spent over a decade in commodities trading and building successful start-ups within the energy and shipping spaces. One of these included setting up a global shipping oil waste collection and recycling business, aimed at increasing waste traceability and transparency standards. This successful business was active in 35 ports in 22 countries with a truly global sustainability footprint. Charlie has a BSc in Business from Imperial College London and a CFA Certificate in Investment Management. Charlie has been featured in publications by The Financial Times, Business Matters, Sustainable Plastics, Energy Connects, Chemical Engineering, among others, and has written several articles for the World Economic Forum’s highly regarded Agenda blog. He is a regular speaker at global events including Reuters Sustainability Conferences, ADIPEC, Economist Impact Sustainability Week, ESF and Davos, and he has been on leading podcasts including Radio Davos, Energy Voice, and Edie’s Sustainability Uncovered. In addition, Charlie co-wrote a globally recognized policy whitepaper on chemical sector decarbonization endorsed by industry CEOs and regulators.

dmg events is a global exhibitions and conferences organiser, with a portfolio of over 80 events focusing on diverse industries, from energy, construction and transport to design and hospitality. More than 425,000 visitors attend our events annually, creating opportunities to network, do business, overcome challenges and discover emerging industry opportunities.
Member of